Buying a Home in Hialeah FL: Efficiencies and Permits
Buying a home in Hialeah FL: how converted garages, efficiency units, older block homes and Miami-Dade rules affect your appraisal and loan approval.
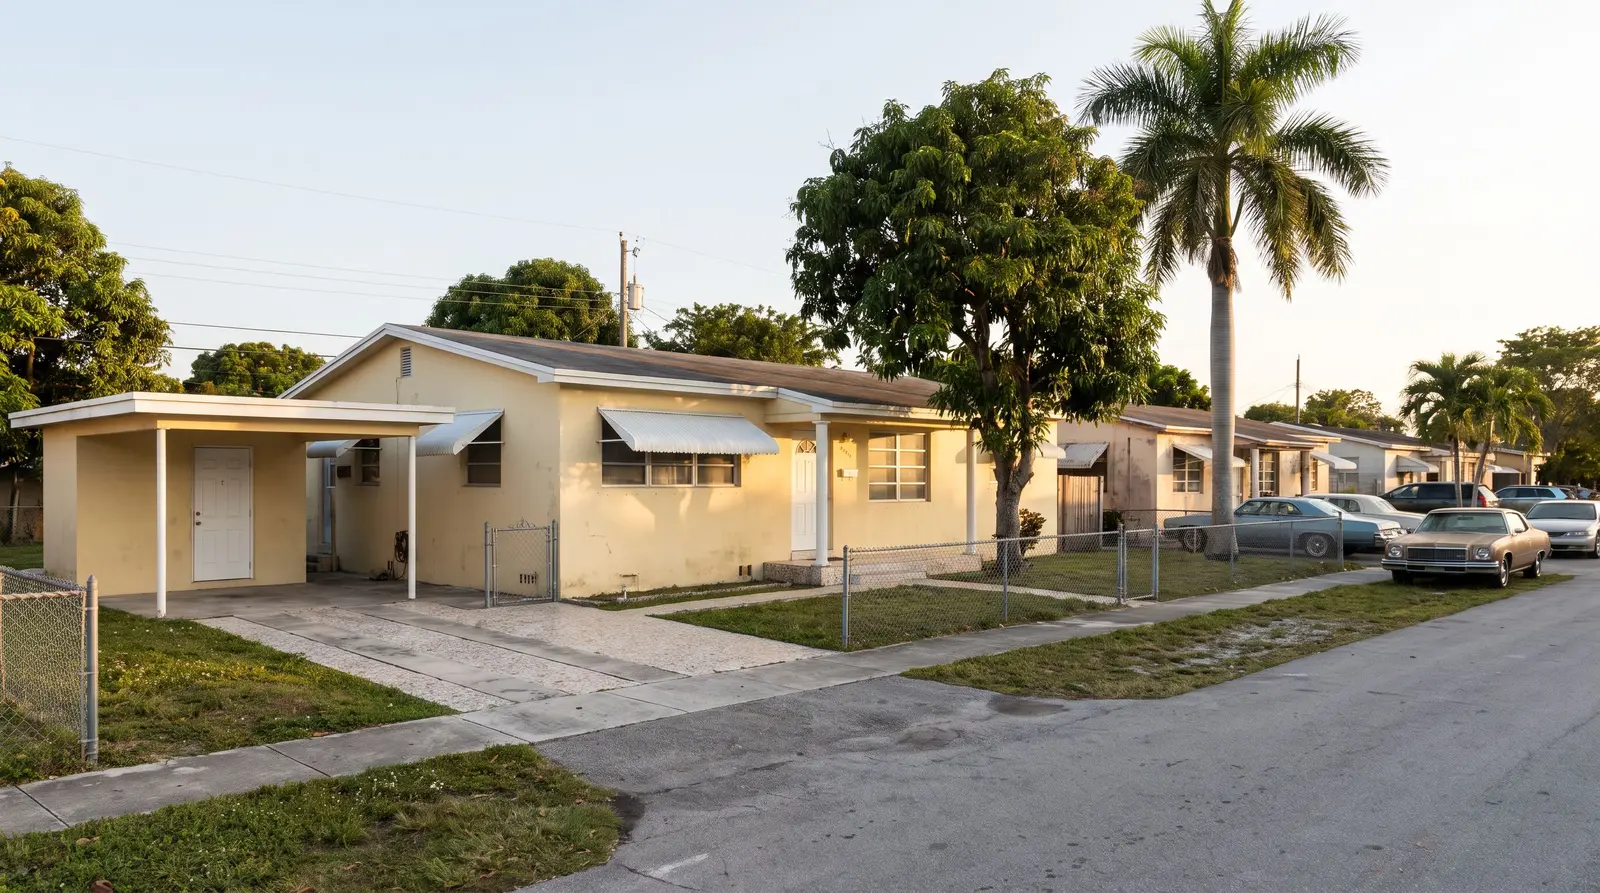
If you are buying a home in Hialeah FL, the question that most often shapes your mortgage is not the price. It is the extra room out back. Many Hialeah houses have a converted garage, an enclosed carport or a rear addition set up as a separate efficiency, and whether that space was permitted decides how the appraiser values it and whether a lender will count any rent from it.
What makes Hialeah different for a lender
Hialeah is one of Miami-Dade's largest cities, and much of its housing is single story concrete block homes built in the 1950s, 60s and 70s, plus duplexes and older low-rise condos. That age profile drives three things in underwriting: added living space of uncertain permit history, insurance on older systems, and condo building reviews.
The loan programs are the same ones you would use in Hollywood or Pembroke Pines. What changes is how much time goes into the property itself. Expect the appraisal and the permit questions to matter more here than on a newer subdivision home in western Broward.
Check the city line too. An address with a Hialeah mailing address can sit in Hialeah Gardens, Miami Lakes or unincorporated Miami-Dade, and each has its own zoning and building department. The rules that apply to an efficiency depend on which jurisdiction the lot is actually in.
Efficiencies, converted garages and the appraisal
An efficiency is a small self-contained unit, usually with its own entrance, kitchen and bathroom, carved out of or added onto a single family home. Lenders call it an accessory dwelling unit, and both Fannie Mae and FHA treat it very differently depending on whether zoning allows it.
Under the Fannie Mae Selling Guide, a one-unit home can have one accessory dwelling unit. An accessory unit is considered legal if current zoning allows it, including as a legal nonconforming use. When zoning does not allow the unit at all, the home can still be eligible, but only if the appraiser shows the use is typical for the neighborhood, values the home on its current use with comparable sales that have the same kind of unit, and the lender confirms the unit will not jeopardize a future insurance claim.
FHA is stricter. Its guidance requires the accessory unit to comply with zoning, which can include a legal nonconforming use. If the efficiency was built without permits and zoning would not allow it, an FHA appraisal can stall until the issue is resolved, which may mean converting the space back or legalizing it. Our FHA loan page explains how the FHA appraisal and property standards work overall.
The practical lesson: a converted garage is not automatically a problem, but an unknown permit history is. Before you write an offer, ask the seller for permits and final inspections on any addition or conversion, and look the address up on the building department's permit search.
Counting rent from an efficiency
Rent from an efficiency can help you qualify, but only under specific program rules. Lenders typically count 75 percent of the rent, and both Fannie Mae and FHA cap accessory unit income at 30 percent of the total income used to qualify you.
Fannie Mae allows it on a one-unit principal residence with one accessory unit, for a purchase or limited cash-out refinance. The appraiser supplies a market rent estimate, and a lease may be needed if a tenant is staying. FHA, under Mortgagee Letter 2023-17, uses 75 percent of the lower of the appraiser's market rent or the lease.
There is a catch you should plan around. These income rules assume the unit itself is acceptable to the program, and many lenders will not count rent from a unit that zoning does not allow. If the efficiency lacks permits, assume you need to qualify on your own income and that the rent is a bonus, not part of your debt to income ratio. Run the payment both ways in our mortgage calculator before you commit.
If the efficiency rent is central to your plan, tell us before you make an offer. Request a quote and a loan officer will check how the specific property is likely to be treated.
When the property is really a duplex
Some Hialeah lots are zoned and built as true duplexes, with two units of roughly equal standing rather than a main house and a small efficiency. The appraiser decides which one you are buying as part of the highest and best use analysis, and that classification changes your loan options.
The difference matters because Fannie Mae does not allow an accessory unit on a two to four unit property. A legal duplex is financed as a two-unit home instead, with its own rules for counting rent and for reserves when you live in one side. Our guide to duplex and triplex financing in South Florida walks through those owner-occupied paths.
If you want to legalize or renovate an existing efficiency as part of the purchase, FHA's 203(k) rehabilitation program can, under the same 2023 guidance, finance adding or renovating an accessory unit. It brings contractor bids, inspections and a longer closing, so it suits buyers with time and a clear scope of work.
Older block homes and your insurance quote
Homeowners insurance on a Hialeah house from the 1950s to 1970s often hinges on the roof and the original systems. Insurance is part of the payment we qualify you on, so a high premium directly reduces how much house fits your debt to income ratio.
Insurers commonly ask for a 4-point inspection on older homes, covering the roof, electrical, plumbing and air conditioning. Original cast iron drain lines, older electrical panels and an aging roof can raise the premium or limit which carriers will write the policy. A wind mitigation report on a block home with newer impact windows or shutters can bring the premium down.
Get an insurance quote while you are still inside your inspection period, not the week before closing. Our guide to Florida homeowners insurance and your mortgage payment explains 4-point inspections and wind mitigation credits in more detail.
Hialeah condos and Miami-Dade closing customs
Hialeah also has a large stock of older low-rise and mid-rise condos, and financing one depends heavily on the building. Florida's milestone inspection law applies to condo buildings three stories or taller, Miami-Dade runs its own recertification program for older buildings, and lenders review reserves and any pending special assessments.
A building with deferred repairs or thin reserves may be non-warrantable for a conventional loan, and FHA requires the project to be on its approved list unless a single-unit approval is available. Our post on Florida condo loans and what changed covers the review in detail.
Closing costs follow Miami-Dade custom. The buyer usually pays for the owner's title policy, and the county surtax on deeds does not apply to a deed for a single family residence. Our breakdown of Miami-Dade versus Broward closing costs shows who pays what. For buyers who need help with cash to close, the Homestead guide explains Miami-Dade's Affordable Homeownership Program, which is open to eligible county residents, including those buying in Hialeah.
Frequently asked questions
Can I get a mortgage on a house with an illegal efficiency in Hialeah?
Sometimes. Fannie Mae can allow a home whose accessory unit zoning does not permit, if the appraiser shows it is typical for the neighborhood and supports value with similar sales. FHA requires the unit to comply with zoning, so an unpermitted efficiency may need to be legalized or converted back first.
Does rent from an efficiency count as income for a mortgage?
It can on a one-unit home where the unit meets program rules. Lenders typically count 75 percent of the rent, capped at 30 percent of your total qualifying income under both Fannie Mae and FHA guidance. Rent from an unpermitted unit is often not counted.
How do I check permits on a Hialeah home before buying?
Confirm which jurisdiction the lot is in, then search that building department's permit records by address. Ask the seller for permits and final inspections for any garage conversion, addition or new roof, and have your inspector flag work that looks unpermitted.
Ready to talk? Get a free quote or call (973) 862-1489 and a licensed loan officer will walk you through it.
Looking for a lender here? Mortgage broker in Hialeah, FL.